Serving your country can provide a pension, healthcare benefits, and opportunities to build wealth. Yet understanding those benefits often requires education that service members never receive. Military financial planning becomes especially important when marriage, divorce, homeownership, and retirement overlap.
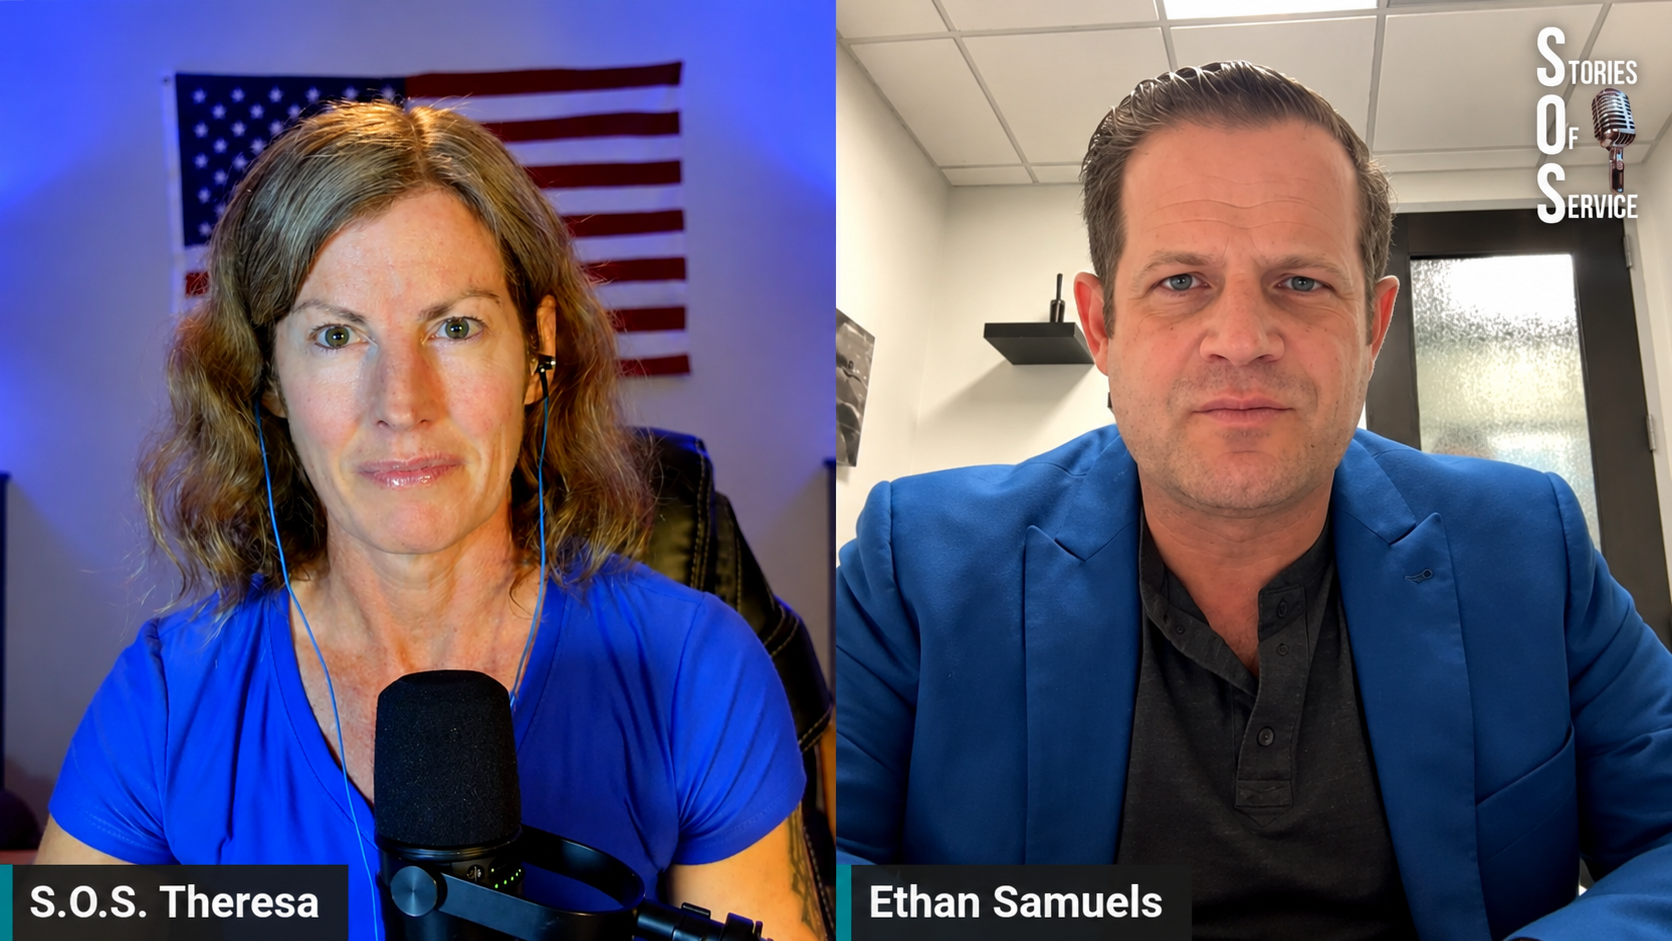
On S.O.S. Stories of Service, host Theresa Carpenter welcomes former Navy intelligence officer Ethan Samuels for a conversation about protecting the financial future of military families. Their discussion explores expensive misunderstandings, overlooked opportunities, and the importance of asking questions before a crisis forces the issue.
Carpenter brings personal experience: after nearly three decades in uniform, she faced unexpected Survivor Benefit Plan deductions from her retirement pay. Her story illustrates how paperwork and unfamiliar rules can affect even experienced military leaders.
WHO IS ETHAN SAMUELS?
Ethan Samuels is a former U.S. Navy intelligence officer and financial strategist with Hoss Financial. Following September 11, he studied Arabic and worked as a civilian translator before joining the Navy, where he developed his ability to turn complex information into practical guidance.
His move into financial planning was shaped by witnessing the difficulties a military family faced after a service member’s death. Today, he helps military members, veterans, and their families better understand their benefits, protect their assets, and prepare for retirement.
From Navy Intelligence to Financial Planning
Samuels grew up in Southern California and felt drawn to service after September 11. He studied Arabic, worked as a civilian translator, and later joined the Navy as an intelligence officer.
He sees a connection between intelligence and financial planning. Both involve translating complicated information into decisions that people can understand and use.
One experience helped shape his financial career. He recalls a senior enlisted leader whose death left a family facing housing and financial difficulties, with outdated estate documents complicating an already painful transition. For Samuels, the lesson was clear: professional responsibility does not automatically translate into personal financial preparedness.
Military Divorce and Survivor Benefits
Carpenter describes discovering that more than $6,000 annually was being deducted for survivor coverage she understood had been waived through an amended divorce decree. Resolving the problem required repeated calls, formal inquiries, and considerable time.
Her experience highlights the importance of understanding court orders and confirming that the appropriate agencies receive required documents. A legal change and an administrative update are separate steps.
Military pension division also requires precision. The Uniformed Services Former Spouses’ Protection Act does not automatically award a former spouse half of a pension. State courts may divide eligible retired pay, and the familiar 10/10 rule concerns eligibility for direct DFAS payments rather than whether a court can make an award.
For military couples, informed planning means getting qualified guidance before signing agreements or making survivor benefit decisions.
TSP Loans Deserve Close Attention
Samuels shares an account of a retired service member whose Thrift Savings Plan loan became a difficult administrative problem. The episode emphasizes how confusing repayment obligations can become during the transition out of uniform.
The practical takeaway is to review current TSP requirements before separating or retiring. Confirm repayment arrangements, track account activity, and retain written records of important communications.
A loan that appears manageable during active duty deserves another review when pay arrangements change. Retirement preparation should include outstanding debts alongside projected income, benefits, and household expenses.
Building Wealth Through Military Real Estate
Carpenter and Samuels discuss buying homes during military assignments and retaining properties as rentals after relocating. Carpenter describes using a property manager to help operate an Airbnb while sharing responsibilities for larger repairs.
For some families, this approach can create additional income and build equity. However, rental ownership also involves vacancies, maintenance, insurance, management fees, and local regulations.
VA home loans can support qualifying home purchases, but another assignment does not automatically provide unlimited fresh entitlement. Additional purchases depend on remaining or restored entitlement, lender approval, and applicable occupancy requirements.
The useful lesson is to evaluate each property as a financial commitment. Reliable cash flow and adequate reserves matter more than simply accumulating addresses across duty stations.
Four Questions for a Financial Advisor
Samuels offers a straightforward way to evaluate financial advice. Does the advisor put your interests first? Do they understand your needs? Do they explain their recommendations and fees? Do they provide regular written updates?
These questions help service members assess whether they are receiving a relationship built around their circumstances.
Military households may have pensions, allowances, disability benefits, retirement accounts, and rental income interacting in different ways. An advisor should explain how recommendations fit that complete picture.
Understanding the plan also helps clients recognize when a promotion, marriage, relocation, or retirement date warrants a new conversation.
Retirement Planning Goes Beyond Investments
The discussion returns repeatedly to taxes, market losses, and inflation. Samuels encourages listeners to think about how money will support their lives after employment ends.
Someone approaching retirement may need a different investment approach from someone with decades remaining in the workforce. Withdrawals, emergency expenses, and the ability to withstand losses deserve attention together.
Healthcare requires similar preparation. For most retirees eligible for premium-free Medicare Part A at 65, Medicare Part B is required to retain TRICARE coverage, with TRICARE For Life providing wraparound coverage. VA healthcare is a separate system.
Checking these arrangements early can help families budget realistically and avoid preventable coverage problems.
Estate Planning Protects Military Families
Samuels emphasizes keeping estate planning documents aligned with current relationships, assets, and wishes. The conversation covers wills, trusts, powers of attorney, medical directives, and arrangements for minor children.
These documents serve different purposes. A family’s needs may change after marriage, divorce, childbirth, relocation, or the purchase of a home.
Reviewing beneficiaries and account access is also part of preparation. Loved ones should know where essential documents are stored and whom to contact when help is needed.
Carpenter and Samuels connect this work to the military habit of protecting others. Clear instructions can reduce uncertainty for families during an already difficult time.
WATCH FULL EPISODE HERE
Start Planning Before Retirement Arrives
This Stories of Service conversation makes military financial planning feel immediate and personal. Carpenter’s experience shows the cost of misunderstood benefits, while Samuels highlights opportunities to make more informed choices throughout a career.
Begin with one manageable step: review a retirement statement, locate estate documents, clarify a benefit election, or prepare questions for a qualified professional. Then share useful information with others in your military community.
Preparing for the future is another way to care for the people who depend on you.
Editor’s Note
This article is based on Ethan Samuels’ conversation with Theresa Carpenter on Stories of Service. Personal experiences shared during the episode reflect individual circumstances. Military benefits, tax rules, and legal requirements can change; readers should verify current guidance and consult qualified professionals before making decisions about their own finances.
Learn More
👥 Connect with Stories of Service Podcast
🔗 Meet Ethan: https://hossfinancial.com/team_member...
📖 My SBP story: https://www.wearethemighty.com/featur...
📖 My spousal support story: https://www.theresatapestries.com/blo...